A pair of shoes costs more than it did last year. So do ground beef, a car repair, and the washing machine that finally died. None of that is random. The average U.S. tariff rate has climbed to 10 to 13 percent, the highest level since the 1940s, and research consistently finds that American buyers, not the countries selling the goods, cover most of that cost. For a growing number of households, covering the difference means swiping a credit card instead of paying cash, and tariffs and debt are climbing together as a result. Here is what tariffs are actually adding to household bills in 2026, and how to keep that added cost from turning into debt that outlasts the tariffs themselves.
Why Tariffs Are Showing Up In Your Budget Right Now
A tariff rarely raises prices the moment it takes effect. Importers and retailers typically absorb the added cost first, then pass it on once their own margins run thin, which is why a 2026 Federal Reserve analysis found the full price increase lands on consumers roughly seven months after a tariff starts, at close to a one-to-one rate. Multiple economic reviews put the total tariff burden on U.S. importers and consumers combined at around 90 percent, versus about 10 percent absorbed by foreign exporters. That pass-through has added close to 0.8 percentage points to the consumer price index since early 2026, pushing inflation to about 3.5 percent, well above the Federal Reserve’s 2 percent target.
Which Purchases Cost More Because Of Tariffs
Yale Budget Lab tracking shows the steepest tariff-driven price increases in motor vehicles and parts, recreational vehicles and boats, clothing and footwear, furniture and home goods, household appliances, kitchenware, electronics, and groceries. Ground beef alone has averaged $6.82 a pound in recent months. None of these are luxury purchases. They are the everyday and big-ticket items a household budget already has little room to absorb, which is one reason more of the added cost is landing on a credit card instead of getting paid in cash.
How Tariffs And Debt Are Feeding Each Other
Tariffs added roughly $1,000 to the average household’s costs in 2025 and are on pace to add close to $700 more in 2026. When a paycheck buys less, the gap commonly gets financed rather than skipped. Credit card debt has already climbed to $1.26 trillion nationwide in 2026, and most cardholders carry a balance from month to month rather than paying it off in full. A tariff-driven price increase that looks small at checkout compounds fast once it sits on a card charging close to 21 percent interest.
Tariff Rates Could Still Change, Your Budget Should Not Wait
The current 10 to 13 percent average tariff rate could fall to 6 to 9 percent if certain tariffs expire without a Congressional extension. It could also hold steady or rise, depending on ongoing trade negotiations and legal challenges working through the courts. That uncertainty is exactly why a household budget should account for tariff costs now instead of waiting for a policy outcome that has no fixed date.
How To Keep Tariffs From Turning Into Debt You Cannot Shake
Track price increases in the categories that hit your own budget hardest, and build that number into your monthly plan instead of discovering it at checkout. Time large purchases like vehicles, appliances, or furniture around sales and planned replacement dates rather than waiting until something breaks, since an emergency purchase carries the least negotiating power and the highest odds of ending up on a card.
According to a 2026 Federal Reserve note on real-time tariff effects, tariff-driven price increases build gradually across many months rather than showing up all at once. A single expensive shopping trip is rarely the full picture. The increase repeats across a year of ordinary purchases, which is why it adds up faster than it feels like it should. Treat any new balance from a tariff-driven purchase the same way you would treat any other credit card debt: write down the amount, the interest rate, and a payoff date, rather than letting it blend into regular spending.
Frequently Asked Questions About Tariffs And Debt
Do Tariffs Directly Add To My Debt?
Not directly. Tariffs raise the price businesses pay to import goods, and businesses pass most of that cost to shoppers. The added cost becomes debt when a household covers the difference with a credit card instead of cash.
How Much Have Tariffs Added To Household Costs In 2026?
Estimates put the added cost near $700 for 2026, on top of roughly $1,000 in 2025, though the exact amount depends on current tariff rates and what a household typically buys.
Which Purchases Are Most Affected By Tariffs?
Motor vehicles, clothing and footwear, furniture, appliances, electronics, and groceries have seen some of the largest tariff-related price increases, according to Yale Budget Lab tracking.
Will Tariff Rates Go Down Later In 2026?
Some tariffs are set to expire without further Congressional action, which would lower the average rate. Ongoing negotiations and legal challenges mean the rate could also hold steady or rise instead.
What Is The Best Way To Pay Off Debt Caused By Tariffs?
Treat it like any other credit card balance. List the amount and interest rate for every card, then use the debt snowball or debt avalanche method to pay it down before new charges pile on top.
Final Thoughts
A single receipt that runs a little higher than it used to is easy to shrug off. A dozen of them financed on a card over a year is not. Tariffs are not going away on a fixed schedule, but a budget that accounts for them now does not have to find out the hard way what an extra $700 does to a credit card balance.
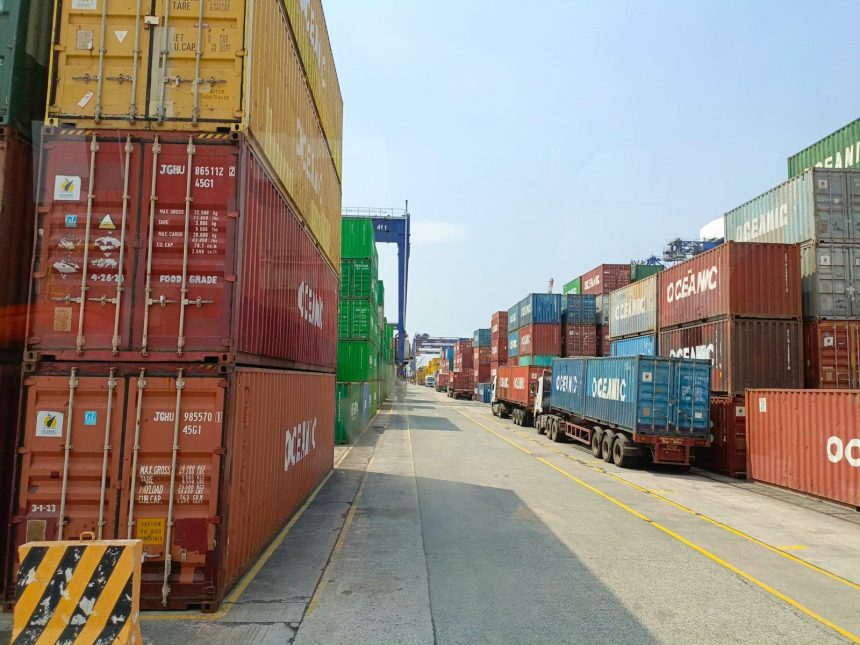
Photo by PortCalls Asia: Unsplash