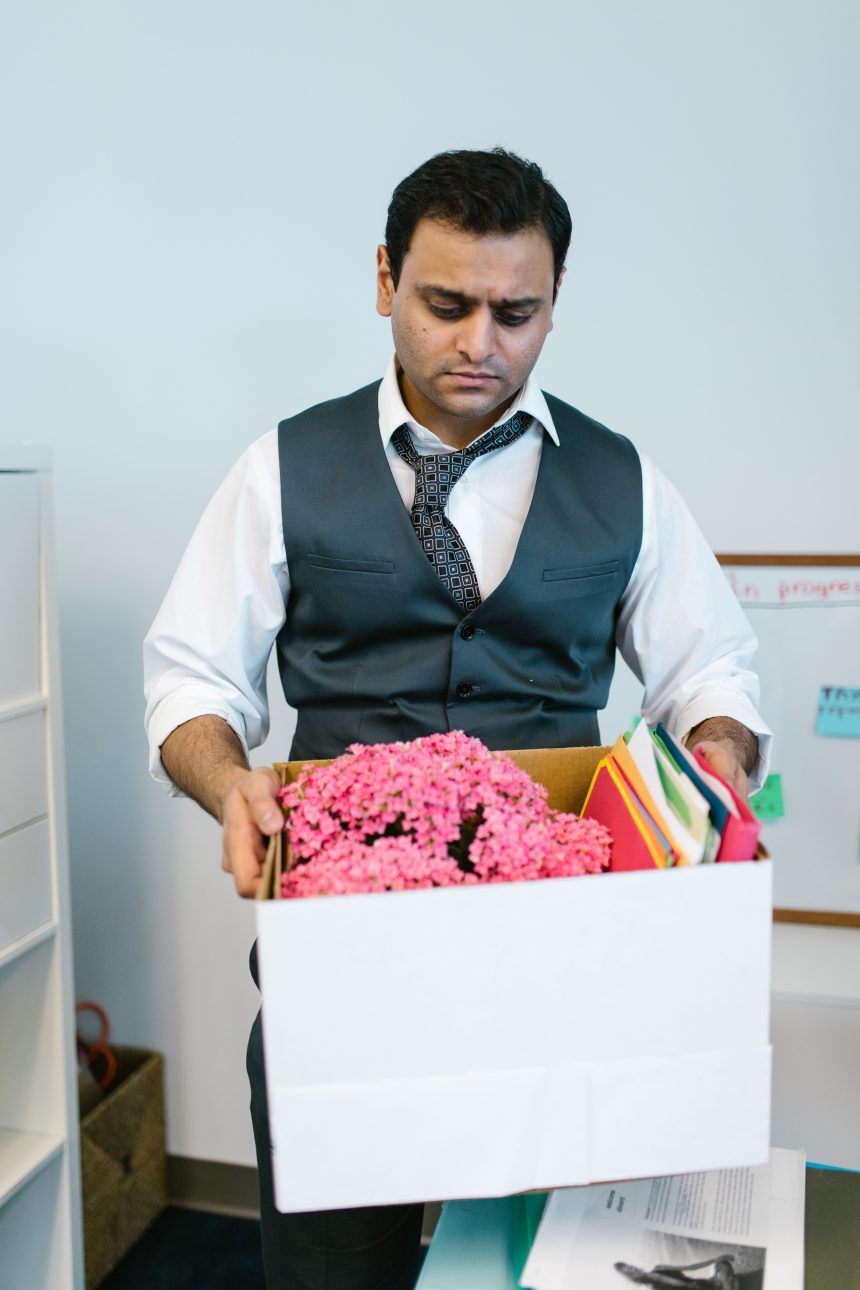
The email lands on a Tuesday afternoon. No warning meeting, no heads-up from your manager. Just a calendar invite titled “Important Update,” and then it’s over. You walk away with a box of desk items and no severance check. Layoffs are climbing again in 2026. For a growing share of workers, the debt that follows a job loss is bigger now. It is harder to escape than it used to be.
Hiring Has Nearly Stalled While Unemployment Climbs
The labor market cooled sharply heading into fall. Employers added just 29,000 jobs in September, far short of the 89,000 economists expected. According to the Bureau of Labor Statistics, that is. The unemployment rate rose to 4.2% from 4.1% the month before. That pushed the number of unemployed workers to about 7.1 million.
The slowdown is not a one-month blip. The average unemployed worker has now been searching for about 24.8 weeks. Meanwhile, the share of people out of work for 27 weeks or longer keeps trending upward. Labor force participation actually ticked up to 61.8%. That means more people are looking for work while fewer jobs open up. That combination keeps pressure on wages. It also makes layoffs far riskier to absorb than they were a year ago.
The slowdown has not landed evenly. The unemployment rate for Black workers rose to 7% in September, up from 6% in August, per BLS data. That is a sharper one-month jump than the overall labor market saw. Economists point to slower hiring and federal workforce reductions as contributing factors. Whatever the cause, layoffs hit hardest on workers who already had the least room in their budgets.
Losing a paycheck during a slowdown like this often means covering rent, groceries, and insurance premiums with a credit card. That happens while a new job search drags on longer than expected. Learning how to handle debt after losing your job, before bills pile up, can help. It can keep a temporary setback from turning into a balance you are still paying off a year later.
Severance Is Disappearing Just When Workers Need It Most
A July 2026 survey of 1,000 laid-off U.S. workers looked at what happens after the paycheck stops. Pollfish fielded it for Resume Genius, and Resume Genius published the results on October 14. Severance pay is no longer something most workers can count on. Forty-eight percent of laid-off women received no severance, benefits, or job placement help. Only 34% of men faced that same gap.
Income made the divide worse. Forty-nine percent of workers earning under $50,000 a year got nothing when they were let go. Among workers earning over $100,000, 62% received severance, and just 21% walked away empty-handed.
The financial fallout showed up fast. Thirty-eight percent of laid-off women drained most or all of their savings after losing their job. Only 30% of men faced the same outcome. Thirty-seven percent fell behind on utility bills, credit cards, and loan payments, compared with 27% of men. Stacie Haller, ResumeBuilder.com’s chief career advisor, said many women still run into bias around career gaps and caregiving duties. That bias prolongs the job search and the financial strain that comes with it.
Roughly a quarter of laid-off workers in the survey leaned on family or friends to get by. That option is not available to everyone equally. Federal Reserve data cited in the survey supports this. About 60% of families in the bottom wealth quintile have that kind of support network. More than 90% of families in the top wealth quintile do. Workers without savings, severance, or help from relatives have fewer places to turn besides a credit card or a loan.
You can read the full breakdown in the BLS September jobs report. It lays out the participation, duration, and demographic numbers behind this slowdown in detail.
What Going Into Debt After a Layoff Actually Looks Like
In practice, this rarely looks like one big financial decision. It looks like swiping a card for the electric bill because unemployment benefits have not started yet. Then it’s groceries the next week. Then it’s a buy-now, pay-later plan for a car repair that cannot wait. Each charge feels manageable on its own. Three months into a job search with no severance behind you, the combined balance often is not.
Retirement accounts take a hit too. Some workers pull from a 401(k) to cover the gap. With an early withdrawal before age 59 and a half, you usually pay income tax. It also adds a 10% penalty. That choice can quietly cost tens of thousands of dollars in future growth. That is on top of whatever was withdrawn just to pay this month’s bills.
The safest cushion against all of this is one you build before the layoff notice arrives. An emergency fund based on your income gives you a realistic savings target. It is based on what you actually earn, not a generic number that may not fit your household.
What to Do First if a Layoff Hits You
File for unemployment benefits the same week you lose your job. Processing takes time, and every week you wait is income you cannot recover. Call your lenders and utility providers before you miss a payment, not after. However, forbearance or a short extension usually only comes if you ask early.
List every fixed expense you have, from rent to insurance to minimum debt payments. Rank them by what happens if you miss one. Losing housing or health coverage costs more than a late fee on a streaming subscription. If you do use a credit card to bridge the gap, track the balance every week. That keeps it from quietly becoming unmanageable before your next paycheck arrives.
Final Thoughts
A layoff is stressful enough without wondering if you will come out the other side buried in new debt. Fewer workers can count on severance to soften that landing in 2026. The gap falls hardest on women, lower earners, and workers without family money to lean on. None of that reflects your effort or financial discipline. Build what buffer you can now. Lean on every public benefit you qualify for if you get laid off. Treat any debt you take on to get through it as temporary, not permanent.
Photo by RDNE Stock project: Pexels